Low Deposit Buyers – don’t let a “low deposit” stop you buying your first home!
There are some good reasons why first-time buyers love working with top mortgage advisors, especially if they’re low deposit buyers that are looking for options.
Introducing Nicola Petersen
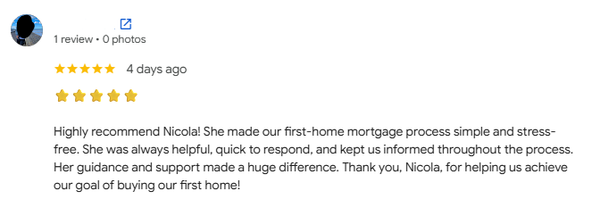
Nicola Petersen has just received another five-star review from a first homebuyer who managed to buy in Auckland with a 5% deposit. We thought we’d share this story because it’s quite typical of the experiences people have, especially with Nicola and the effort she puts into helping people.
This particular couple approached Nicola after speaking with two other advisors and their bank.
They have been saving hard and had managed to save a deposit of 5%, but were not sure what was actually possible and wanted someone to guide them through the process in a step-by-step manner.
Like all first-home buyers, this couple that had never taken on a financial commitment like this before.
Nicola didn’t just jump in to arranging their finances – she first worked through their numbers, discussed the options, and explained what buying with a low deposit would mean for them. Time was spent looking closely at the repayments and understanding what that would mean for their budget.
This couple wanted to make sure that buying a house was not going to cripple them financially, so they really wanted to know that it could work well for them.
What Are Low Deposit Buyers?
In New Zealand, the Reserve Bank of New Zealand uses Loan-to-Value Ratio (LVR) restrictions to define what low-deposit buyers are. The definition of low deposit lending for first home buyers includes anyone with less than 20% deposit.
These “speed limits” also cap the portion of new housing loans banks can give to high-risk, low-deposit buyers (borrowers) and banks can currently use up to 25% of their total new lending for buyers that have less than 20% deposit unless the buyer is “exempt” from the LVR rules.
There are some exemptions to LVR rules and for first home buyers these include Kāinga Ora First Home Loans and Construction Loans – applies when the borrower is constructing a new home or is purchasing a newly built home from the developer within 6 months of completion.
In summary, any buyer with less than 20% deposit is considered a low deposit buyer.
Like a lot of first-time buyers in Auckland, they went looking at properties and initially found a home that they loved. The home was built with monolithic cladding, which put it in a high-risk category for weather tightness. In a lot of cases, monolithic cladding-clad properties do appear to be good value for money because they are sold at a discounted rate when compared to other more robust structures, and in this case, they loved the interior with the nice kitchen and the ensuite.
Nicola highlighted the risks with them and suggested they get a building report, which they did, and unfortunately or fortunately, it highlighted some issues with the building. The couple are not risk-takers and understood that it would not be wise to proceed with that purchase, so they walked away and kept looking.
They eventually did find something more suitable, and are now proud new owners of a home they purchased for $850,000 with a 5% deposit.
They are now very happy to be homeowners and are now focused on paying their mortgage off faster. Their initial aim is to get 20% equity in the property.
Nicola worked with them to create a loan structure that enables them to reduce their mortgage without the risks of penalties and without the risk of being trapped into higher repayments should interest rates increase.
Get Good Mortgage Advice
Giving good mortgage advice is more than just crunching the numbers.
It’s about making sure that the purchasers (borrowers) are happy with the whole process even if they are low deposit buyers and obviously everyone wants a home loan approval and then the longer term outcome too.
Many first home buyers are going to be nervous, and that’s quite a natural thing. You want to make sure that you’re working with a mortgage advisor that has your best interests top of mind, can answer all of your questions, and help you work through any concerns you might have.
Nicola got another five-star review from these very happy clients.
Maybe you should be working with an advisor like Nicola too.